Stakeholder Theory (R. Edward Freeman)
🗂️ Interactive Notebook: Open Study Companion (Video Summary, Flashcards, Mind Map) ↗
Stakeholder Theory, formulated by philosopher and management scholar R. Edward Freeman in his landmark 1984 treatise Strategic Management: A Stakeholder Approach, posits that a corporation is an organic nexus of interdependent human relationships whose central purpose is to generate sustainable, multidimensional value for all constituents who affect or are affected by its operations. Serving as the primary theoretical counterweight to Anglo-American shareholder primacy, the framework integrates normative moral philosophy with practical strategic management, rejecting the assumption that commercial value creation and ethical responsibility can be meaningfully separated.
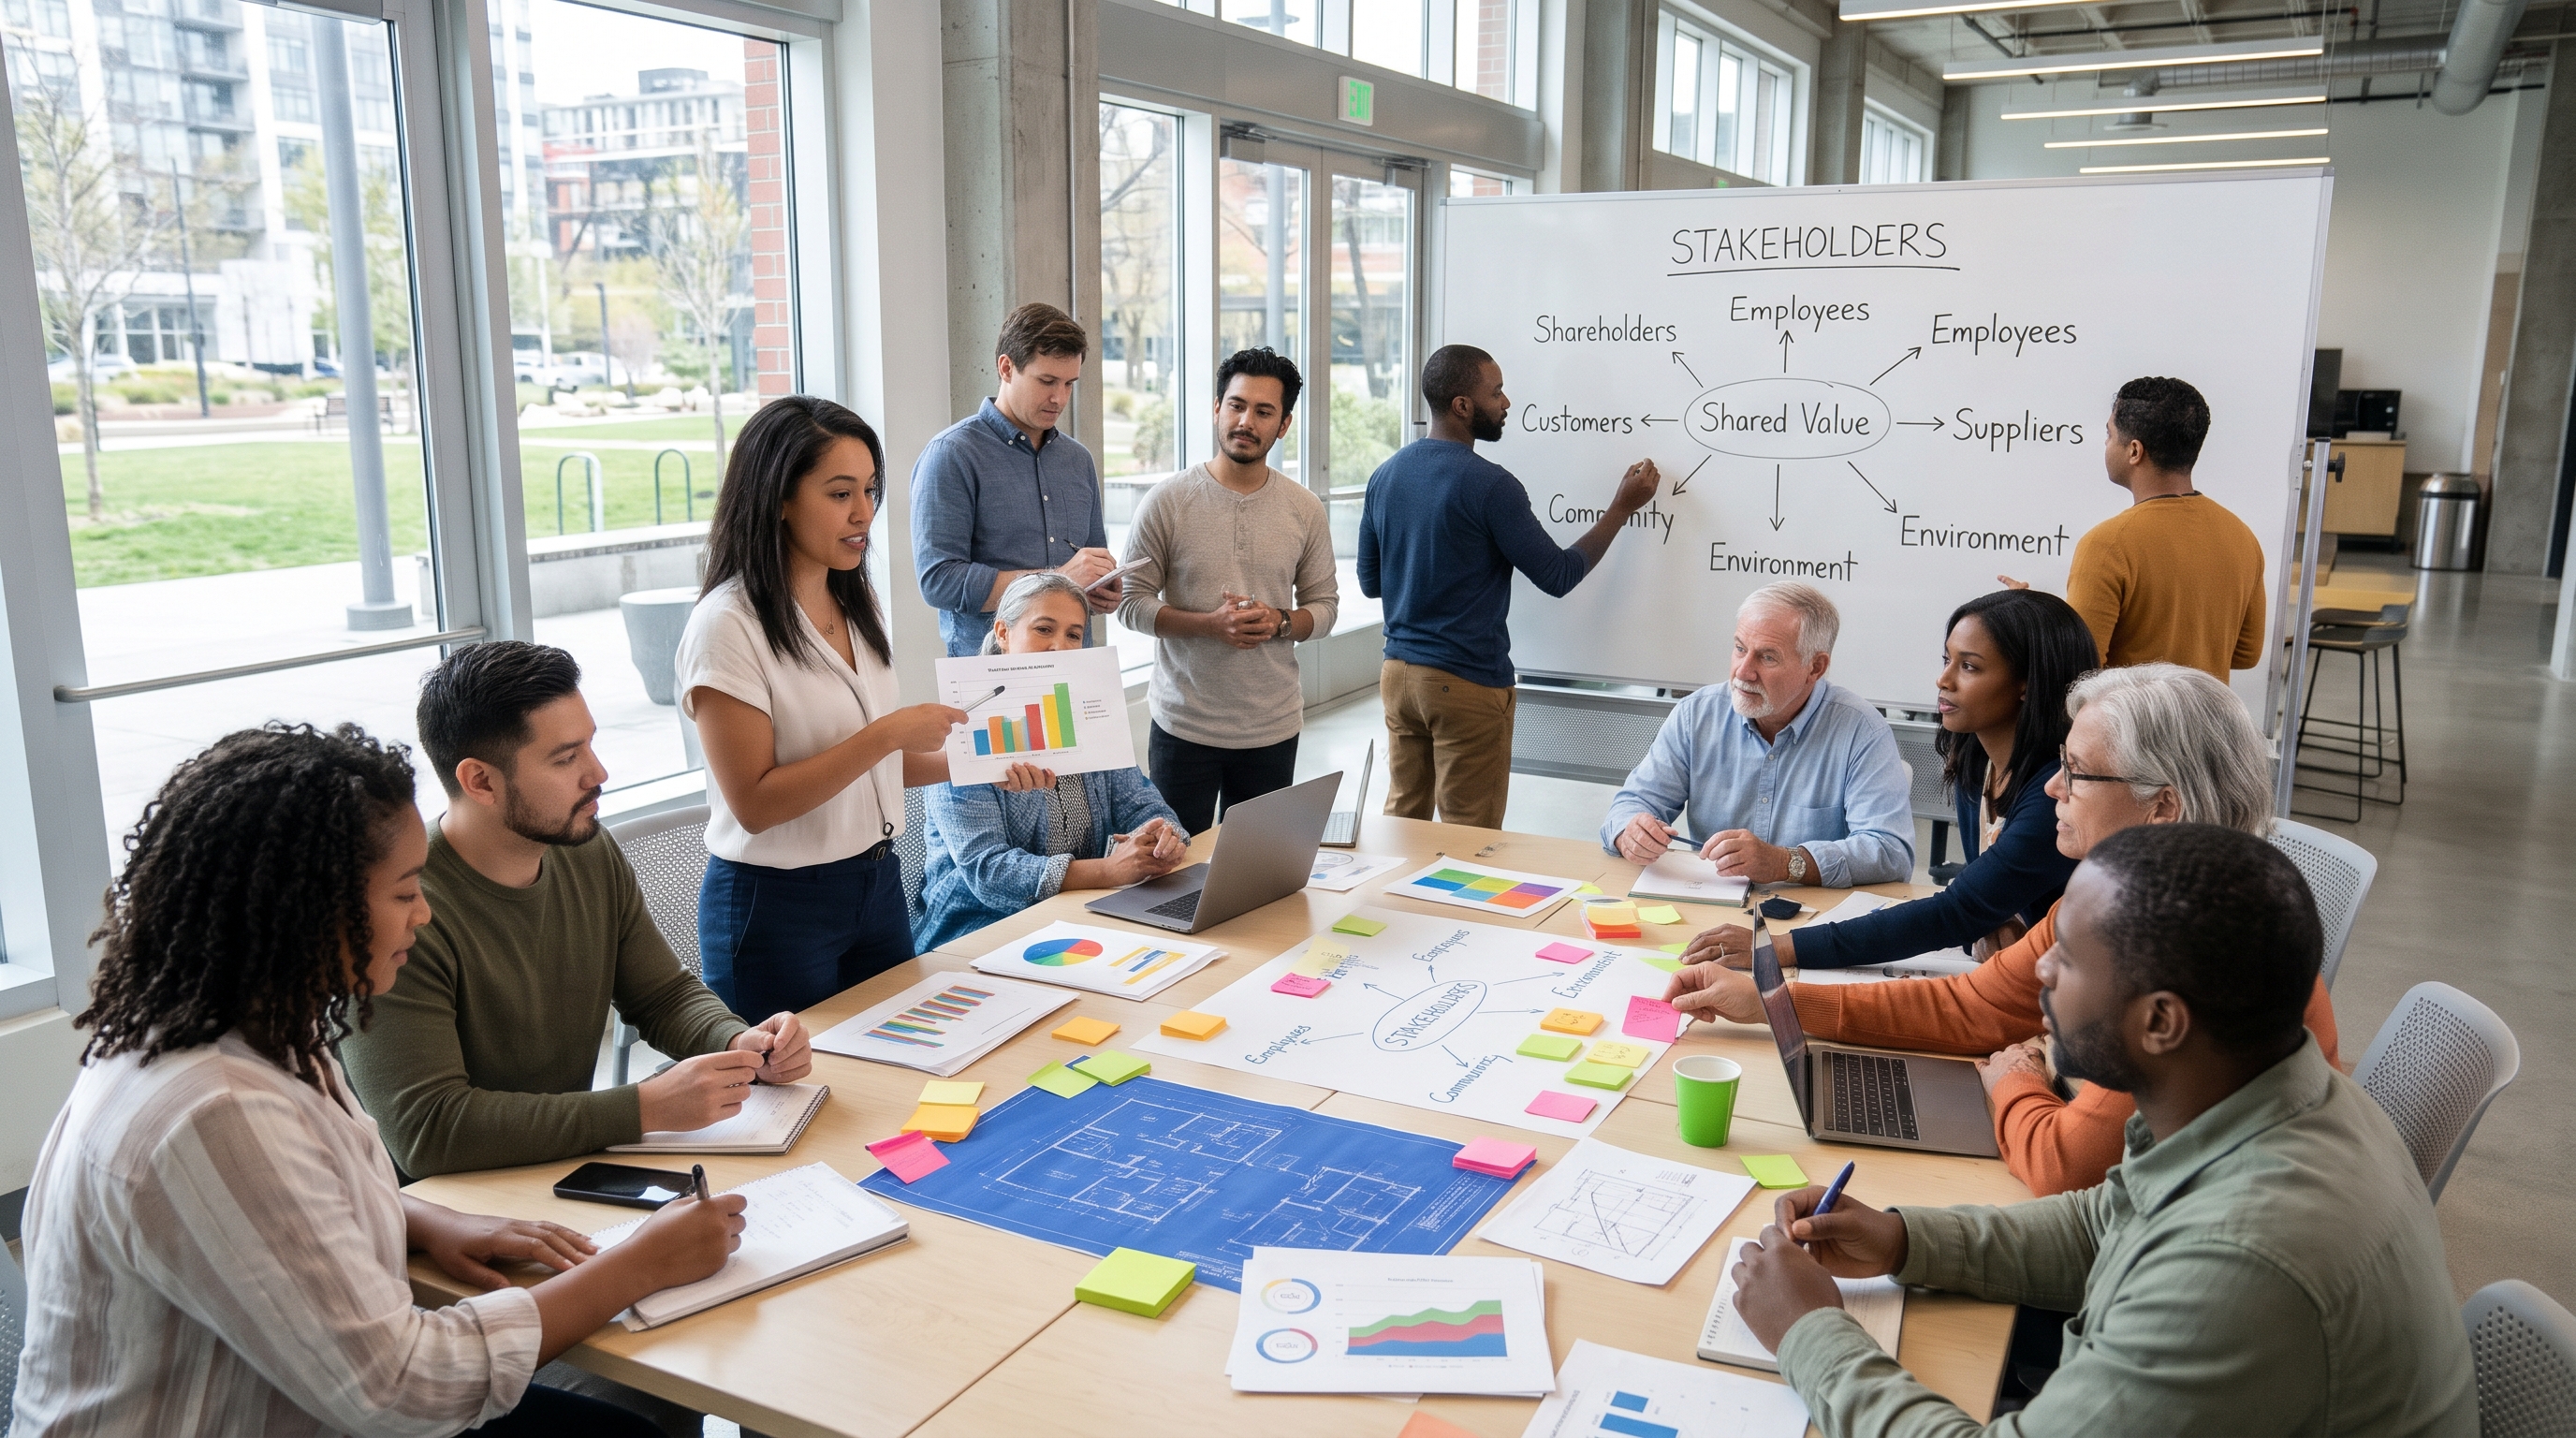
1. Historical Origins and the Shifting Strategic Paradigm
During the post-World War II era, corporate management was predominantly viewed through the lens of managerialism: executives acted as professional trustees balancing the demands of organized labor, local communities, capital providers, and the state. However, by the 1970s, the ascendancy of the Chicago School of Economics and Milton Friedman's formulation of shareholder primacy (see Shareholder Primacy (Milton Friedman)) fundamentally transformed corporate governance, narrowing corporate duty exclusively to the maximization of equity returns.
In response to the resulting short-termism, hostile takeover waves, and systemic negative externalities, R. Edward Freeman—a philosopher trained in pragmatism and phenomenology teaching at the University of Virginia's Darden School of Business—sought to construct an alternative operational paradigm.
The Stanford Research Institute Precursor (1963)
The terminology of the "stakeholder" was first coined internally at the Stanford Research Institute (SRI) in 1963. SRI researchers introduced the term as a deliberate linguistic play on "stockholder," defining stakeholders as:
"Those groups without whose support the organization would cease to exist."
SRI's early formulation was primarily defensive and instrumental: corporate planners were urged to identify external interest groups (such as banks, key suppliers, and labor unions) whose resistance could derail corporate strategy.
Freeman’s 1984 Landmark Formulation
In Strategic Management: A Stakeholder Approach (1984), Freeman elevated the concept from a defensive risk-management tactic to an overarching philosophy of management and enterprise strategy. Freeman observed that the business landscape had undergone unprecedented environmental turbulence: globalization, aggressive deregulation, environmental consciousness, rapid technological shifts, and consumer activism rendered traditional closed-system management obsolete.
Freeman replaced the simplistic input-output production model of the firm with the Stakeholder Ecosystem Model, illustrating the modern corporation at the center of a dynamic web of mutual obligations:
- Primary / Core Constituents: Financiers (shareholders, bondholders), employees, customers, suppliers, and local communities.
- Secondary / Extended Constituents: Government bodies, regulatory authorities, trade associations, environmental organizations, media, and competitors.
Rather than treating the corporation as the private property of equity investors, Freeman conceptualized it as a collaborative institution embedded within civil society.
2. Foundational Philosophical and Theoretical Pillars
Freeman's stakeholder framework differs from standard managerial models because it is explicitly grounded in normative moral philosophy and American philosophical pragmatism. It rests on five central conceptual pillars:
1. Broad vs. Narrow Definitions of Stakeholders
Freeman articulated two complementary definitions to clarify managerial scope:
- The Broad Definition (Strategic & Empirical): "Any group or individual who can affect or is affected by the achievement of the organization's objectives." This captures extended actors such as investigative journalists, environmental NGOs, community activists, and regulatory agencies who possess the capacity to exert structural influence on the enterprise.
- The Narrow Definition (Vital & Contractual): "Any group or individual that is vital to the survival and success of the corporation." This encompasses customers, employees, suppliers, communities, and financiers without whose continuous reciprocal cooperation the firm collapses.
2. The Separation Fallacy
Freeman delivered a sweeping critique of what he termed the "Separation Fallacy"—the ubiquitous assumption in conventional economics and business school curricula that commercial decisions can be cleanly divorced from moral questions. Under this orthodox fallacy, managers make "purely business" decisions governed by market calculus, treating ethics as an optional, secondary constraint or an ex-post corporate social responsibility (CSR) exercise.
Freeman argued that the separation fallacy is epistemologically incoherent:
- Every commercial business decision—from closing a manufacturing facility to pricing life-saving pharmaceuticals or automating warehouse labor—distributes benefits and harms, generates risks, and impacts human rights. It is inherently normative.
- Conversely, every ethical judgment regarding human welfare, justice, and community flourishing requires material resources and economic viability to be sustained in practice.
- Therefore, strategy and ethics are co-constitutive: business is intrinsically a moral human endeavor.
3. The Open Question Argument
Borrowing from moral philosopher G. E. Moore's classic ethical critique, Freeman formulated the Open Question Argument in corporate strategy. For any business proposal, operational initiative, or financial transaction
- If this decision is carried out, for whom is value created and for whom is value destroyed?
- Who is harmed and who is benefited?
- Whose rights are respected and whose are violated?
- What kind of community or society are we actively constructing through this practice?
If corporate activity were reducible to mechanical profit maximization, these questions would be irrelevant or settled by balance sheet metrics. Because they remain perpetually open and urgent, business strategy cannot escape moral justification.
4. The Principle of Who or What Really Counts: Stakeholders as Ends in Themselves
Conventional financial theory tolerates stakeholder engagement strictly through an instrumental lens: executives should treat employees fairly or placate regulators only to the extent that doing so mitigates operational friction and enhances equity value.
Drawing upon Immanuel Kant's practical imperative—which demands that humanity always be treated as an end, never merely as a means—Freeman argued that stakeholders possess intrinsic value. Employees, suppliers, and local citizens are moral persons with inherent dignity, life projects, and legitimate rights. Their welfare cannot be treated as an expendable variable or raw input to be discarded whenever financial engineering dictates a short-term stock boost.
5. Jointness of Interests and Rejection of the Trade-Off Mentality
The orthodox paradigm of shareholder primacy is rooted in a zero-sum trade-off worldview: capital versus labor, supplier margins versus firm profits, environmental protection versus corporate earnings.
Freeman vigorously rejected this trade-off mentality, asserting that the defining competence of an executive is value creation synergy (the principle of "jointness"):
- The managerial task is not to adjudicate zero-sum compromises, but to redesign business models so that stakeholder interests are aligned and reinforce one another.
- Excellent management seeks solutions where improving employee compensation and dignity drives product quality, which delights customers, which strengthens supplier loyalty, which generates durable, compounding returns for investors.
- Trade-offs are a symptom of uninspired, unimaginative leadership, not an unavoidable law of nature.
3. Theoretical Taxonomies: Donaldson & Preston's Typology and Stakeholder Salience
As Stakeholder Theory gained traction, organizational scholars developed rigorous analytical taxonomies to structure its empirical and operational application.
Donaldson and Preston’s Tripartite Typology (1995)
In their influential Academy of Management Review paper, Thomas Donaldson and Lee Preston clarified that Stakeholder Theory operates across three distinct, nested methodological levels:
| Dimension | Core Question | Epistemological Nature | Operational Application |
|---|---|---|---|
| Descriptive / Empirical | How do organizations actually behave? | Factual observation | Maps how managers describe their roles, identify stakeholder groups, and trace corporate resource flows. |
| Instrumental | What happens if managers manage for stakeholders? | Pragmatic correlation | Tests empirical hypotheses connecting stakeholder satisfaction to financial metrics (ROE, Tobin's Q, brand equity, employee retention). |
| Normative (The Core) | Why should corporations treat stakeholders with dignity? | Moral philosophy | Establishes the underlying ethical foundation: stakeholders have legitimate moral claims that command respect regardless of instrumental utility. |
Donaldson and Preston established that the normative level forms the foundational core: instrumental and descriptive models are ultimately anchored to philosophical convictions about human dignity and justice.
Mitchell, Agle, and Wood’s Stakeholder Salience Framework (1997)
To resolve the managerial challenge of prioritizing competing claims in fast-moving operational settings, Ronald Mitchell, Bradley Agle, and Donna Wood introduced the Stakeholder Salience Model, assessing stakeholder groups across three structural attributes:
- Power: The ability of a group to bring about its desired outcomes using coercive (physical/forceful), utilitarian (financial/material), or normative (symbolic/social) means.
- Legitimacy: The generalized perception or assumption that a group's claims, behavior, or structures are socially desirable, proper, or appropriate within a system of norms and values.
- Urgency: The degree to which a stakeholder's claim calls for immediate attention, determined by time-sensitivity (critical delays cause damage) and criticality (the claim is vital to the claimant).
By mapping the intersection of these three attributes, managers classify constituents into seven discrete stakeholder categories:
- Latent Stakeholders (Possessing 1 Attribute):
- Dormant (Power only): Retain latent coercive or financial muscle but lack legitimacy or immediate claims (e.g., prospective corporate raiders, disgruntled former executives).
- Discretionary (Legitimacy only): Possess legitimate standing but lack power or urgent demands (e.g., local educational non-profits, philanthropic recipients).
- Demanding (Urgency only): Highly vocal and time-sensitive claimants lacking power or recognized legitimacy (e.g., fringe activist demonstrators).
- Expectant Stakeholders (Possessing 2 Attributes):
- Dominant (Power + Legitimacy): Institutional actors whose claims are both legally/morally sanctioned and backed by material influence (e.g., boards of directors, sovereign creditors, major institutional investors).
- Dangerous (Power + Urgency): Coercive actors operating without institutional legitimacy whose immediate demands pose existential threats (e.g., wildcat strikers, sabotaging hackers, hostile blockaders).
- Dependent (Legitimacy + Urgency): Vulnerable groups whose urgent, legitimate claims depend entirely on third-party advocates for enforcement (e.g., local communities affected by toxic chemical spills, wildlife habitats).
- Definitive Stakeholders (Possessing all 3 Attributes):
- Definitive (Power + Legitimacy + Urgency): High-priority constituents whose demands require immediate executive action and capital allocation (e.g., unified regulatory enforcement agencies issuing cease-and-desist orders, mobilized workforces striking over life-safety violations).
4. Freeman vs. Friedman: The Clash of Corporate Governance Paradigms
The tension between Milton Friedman's Shareholder Primacy (see Shareholder Primacy (Milton Friedman)) and R. Edward Freeman's Stakeholder Theory represents the defining intellectual debate of modern political economy and business administration:
| Strategic Dimension | Shareholder Primacy (Milton Friedman) | Stakeholder Theory (R. Edward Freeman) |
|---|---|---|
| Ultimate Purpose of the Firm | Maximize financial profits and residual equity value for stockholders. | Create, balance, and distribute multidimensional value across all constituent networks. |
| Primary Fiduciary Duty | Owed strictly to equity shareholders as the legal owners and residual claimants. | Multi-fiduciary duty owed to the ongoing enterprise and all interdependent stakeholders. |
| Integration of Ethics | Extraneous; ethics is a compliance filter or philanthropic add-on. | Indivisible from strategy; rejects the separation fallacy between business and morality. |
| View of Non-Investors | Instrumental: human labor, supply chains, and communities are means to financial ends. | Inherent: stakeholders possess intrinsic validity and must be treated as ends in themselves. |
| Concept of Strategy | Competitive war of positioning and asset extraction to generate economic rents. | An authentic value-creation story harmonizing joint stakeholder interests. |
| Time Horizon | Short-to-medium term; driven by quarterly consensus earnings, EPS, and market cycles. | Intergenerational; anchored to long-term operational resilience and ecosystem survival. |
| Capital Allocation Metric | Return on Equity (ROE), Net Present Value (NPV), and open-market share repurchases. | Balanced Scorecards, Triple Bottom Line (People, Planet, Profit), and ESG performance. |
| Governance Architecture | Single-tier boards dominated by shareholder representatives and equity incentives. | Multi-stakeholder oversight, employee codetermination, and stakeholder advisory boards. |
| Systemic Failure Mode | Quarterly capitalism, asset stripping, negative externalities, and systemic fragility. | Diffuse accountability, ambiguous trade-off rules, and managerial paralysis. |
5. Corporate Governance, Multi-Fiduciary Duty, and Strategic Narrative
Translating Stakeholder Theory into practical operational reality requires restructuring traditional corporate governance, performance incentives, and managerial leadership models.
Multi-Fiduciary Duty
Traditional Anglo-American corporate law treats directors as agents of the shareholders. In contrast, Freeman's framework conceptualizes directors and executive officers as fiduciaries of the enterprise itself. Their duty is not to serve as conduits for short-term shareholder extraction, but to steward the durable health, knowledge assets, and social license of the corporation across generations.
Strategy as a Narrative of Purpose
Freeman emphasized that strategic management is not a sterile mathematical exercise in financial optimization; it is fundamentally a narrative art. Successful enterprises craft a compelling "value-creation story" answering three fundamental questions:
- What shared purpose brings this community of stakeholders together?
- How do our daily operations generate tangible value for our customers, dignity for our employees, and vitality for our suppliers?
- What kind of relationships are we building with society and the living biosphere?
When leadership articulates a purpose that resonates with all stakeholder groups, it unlocks discretionary effort from labor, fierce brand loyalty from consumers, collaborative innovation from suppliers, and patient long-term capital from values-aligned investors.
Institutional Mechanisms of Implementation
Organizations committed to operationalizing stakeholder principles deploy concrete structural mechanisms:
- European Codetermination (Mitbestimmung): Under German corporate governance law, large enterprises operate a dual-board system where up to 50% of supervisory board seats are elected directly by the workforce, institutionalizing labor as a primary governance partner (see Difference Between a Shareholder and a Stakeholder).
- Benefit Corporation (B Corp) Legal Architecture: Traditional corporate charters in Delaware and other common-law jurisdictions risk shareholder derivative litigation if directors subordinate short-term profits to social or environmental goods. Benefit Corporation statutes formally amend corporate charters, legally requiring fiduciaries to balance general public benefit alongside shareholder returns.
- Multidimensional Performance Accounting: Replacing narrow quarterly earnings metrics with integrated reporting systems, including Kaplan and Norton's Balanced Scorecard (see The Balanced Scorecard (Kaplan & Norton)), John Elkington's Triple Bottom Line, and formal sustainability disclosure standards (ISSB, European CSRD, GRI).
- Executive Compensation Realignment: De-emphasizing stock options and short-term share price targets in favor of multi-year scorecards tied to employee safety and retention, carbon footprint reduction, customer Net Promoter Scores (NPS), and supply-chain integrity.
6. Theoretical Critiques, Governance Dilemmas, and Agency Hazards
Despite its widespread popularity, Stakeholder Theory has faced fierce resistance from legal scholars, neo-institutional economists, and financial theorists.
1. The Objective Function / Decision Rule Problem
The most formidable critique of Stakeholder Theory was formulated by financial economist Michael Jensen (Value Maximization, Stakeholder Theory, and the Corporate Objective Function, 2001). Jensen argued that an organization cannot maximize multiple independent variables simultaneously without a single, mathematically defined objective function.
When an executive is told to maximize customer satisfaction, employee wages, community well-being, and shareholder returns at the same time:
- The theory offers no logical decision rule to adjudicate trade-offs when claims inevitably collide.
- For example, if maintaining obsolete manufacturing jobs threatens corporate solvency, how much capital should be sacrificed before closure is warranted?
- Jensen proposed "Enlightened Value Maximization," arguing that long-term firm value remains the only coherent yardstick, even while acknowledging that long-term value requires satisfying key stakeholders.
2. Agency Hazards and Managerial Entrenchment
Legal scholars Lucian Bebchuk and Roberto Tallarita (The Illusory Promise of Stakeholder Governance, 2020) demonstrated that stakeholder governance creates severe agency problems. Under the shareholder primacy model, managers are held accountable to a transparent financial benchmark.
When directors are granted expansive discretion to balance diverse stakeholders:
- Self-interested executives can justify virtually any managerial failure, pet project, or lagging performance under the vague pretext of "investing in stakeholders."
- Conversely, executives can refuse lucrative takeover bids that would benefit shareholders by self-servingly claiming they are protecting employee jobs or community interests.
- In practice, stakeholder rhetoric can insulate entrenched management from shareholder discipline without conferring meaningful decision-making power or economic surplus to non-investor stakeholders.
3. Jurisprudential Constraints in Anglo-American Law
In Delaware corporate jurisprudence—which governs the majority of U.S. publicly traded corporations—the legal reality remains substantially anchored to shareholder welfare. Under landmark precedents such as Dodge v. Ford Motor Co. (1919) and Revlon, Inc. v. MacAndrews & Forbes Holdings, Inc. (1986), directors may consider non-shareholder constituencies only insofar as doing so rationally advances long-term shareholder value.
While the Business Judgment Rule provides broad leeway for stakeholder investments during ordinary operations, a board that explicitly subordinates shareholder wealth to public social goods without charter protection remains vulnerable to breach of fiduciary duty lawsuits.
4. Rhetorical Camouflage and the Reality of "Greenwashing"
When 181 chief executives signed the Business Roundtable's updated Statement on the Purpose of a Corporation in August 2019, it was celebrated as the death knell of shareholder primacy. However, empirical follow-up studies by Bebchuk and Tallarita revealed that:
- Virtually none of the signatory corporations consulted their boards of directors before signing;
- Corporate bylaws were not formally amended;
- Executive compensation plans remained almost exclusively tied to share price metrics;
- During the subsequent economic dislocations of 2020–2022, signatory firms laid off employees and protected shareholder buybacks at rates indistinguishable from non-signatories.
This underscores the risk that stakeholder capitalism can devolve into rhetorical camouflage, offering public relations polish without structural governance reform.
7. The 21st-Century Landscape: From Bilateral Management to Ecosystem Orchestration
In the contemporary global economy, the debate between shareholder primacy and stakeholder theory is no longer merely theoretical. Accelerating systemic shocks—including anthropogenic climate disruption, geopolitical fragmentation, pandemics, and rapid artificial intelligence automation—have exposed the profound fragility of financialized, short-termist business models.
The World Economic Forum and Davos Manifesto 2020
At the 50th annual meeting of the World Economic Forum, Klaus Schwab released the Davos Manifesto 2020, formally enshrining Stakeholder Capitalism as the global blueprint for modern enterprise:
"The purpose of a company is to engage all its stakeholders in shared and sustained value creation. In creating such value, a company serves not only its shareholders, but all its stakeholders—employees, customers, suppliers, local communities, and society at large."
Ecosystem Orchestration
Modern strategic management has increasingly transitioned from bilateral stakeholder management (managing each relationship in a separate silo) to ecosystem orchestration (see IBM - The Corporate Ecosystem and Innovation Ecosystems). In complex platform environments—such as open-source software, electric vehicle charging networks, and biopharmaceutical research consortia—value is co-created across decentralized webs of complementors, users, regulatory bodies, and academic institutions.
Under this modern realization of Freeman's vision, an enterprise is not a private financial extraction engine; it is a foundational social institution whose enduring survival relies upon the vitality, trust, and shared prosperity of the entire planetary ecosystem.
🎴 Interactive Web Practice (Comprehension Check)
Question 1 (The Separation Fallacy & Moral Epistemology): Why does R. Edward Freeman argue that the conventional economic distinction between "business decisions" and "ethical decisions" is fundamentally incoherent?
Answer: Freeman critiques the "Separation Fallacy"—the widespread assumption that commercial strategy and moral ethics operate in isolated, independent spheres. He demonstrates that virtually every operational business decision (such as facility relocations, wage structures, product sourcing, and automation) intrinsically allocates benefits, distributes harms, and impacts human rights, making it inherently normative. Conversely, ethical values cannot be realized without material resources, production systems, and economic viability. By dismantling the separation fallacy, Freeman establishes that business strategy is always already an applied moral endeavor, rendering the idea of a purely "amoral" business decision epistemologically bankrupt.
Question 2 (The Tripartite Typology & The Primacy of Normative Core): In Donaldson and Preston's (1995) tripartite taxonomy of Stakeholder Theory, how do the descriptive, instrumental, and normative dimensions interrelate, and why is the normative core primary?
Answer: Donaldson and Preston divide Stakeholder Theory into three nested dimensions: Descriptive/Empirical (observing and describing how corporations and managers actually interact with various constituencies), Instrumental (testing whether managing for stakeholders correlates with achieving traditional business outcomes like profitability and market value), and Normative (establishing the philosophical justification for why stakeholders possess legitimate moral claims). The normative core is foundational because instrumental arguments rely on expediency—treating stakeholders well only as long as it generates profit. If treating a stakeholder group poorly proved more lucrative, an instrumental framework would endorse exploitation. The normative core anchors the theory in Kantian ethics, asserting that human stakeholders possess intrinsic dignity and must be treated as ends in themselves, establishing moral obligations that precede and govern financial calculations.
Question 3 (Agency Critiques & The Objective Function Dilemma): What primary theoretical and governance objections did Michael Jensen and modern legal scholars like Bebchuk and Tallarita raise against the operationalization of Stakeholder Theory?
Answer: Critics raise two structural challenges. First, Michael Jensen highlights the Objective Function Dilemma: an enterprise cannot maximize multiple independent, conflicting goals simultaneously without an objective decision rule to resolve inevitable trade-offs. Without a single yardstick (such as long-term firm value), managers lack rational criteria to balance competing stakeholder claims. Second, Bebchuk and Tallarita diagnose severe Agency Hazards and Managerial Entrenchment: without clear accountability to shareholders, self-interested corporate executives can exploit vague stakeholder rhetoric to justify financial underperformance, defend perquisites, and insulate themselves from hostile takeovers, all while conferring no legally enforceable rights or tangible benefits upon non-investor stakeholders.
Resonant Notes
The following notes in the vault share direct thematic, corporate governance, and ethical connections with Stakeholder Theory (R. Edward Freeman):
🔴 Corporate Governance, Agency Theory & Legal Foundations
- Shareholder Primacy (Milton Friedman) — The definitive intellectual adversary to Freeman's framework, asserting that an enterprise's sole social duty is maximizing financial returns for equity owners within the bounds of law.
- Difference Between a Shareholder and a Stakeholder — Establishes the core legal, financial, and relational distinctions separating equity owners with residual claims from broader societal constituencies.
- IBM - International Business Law — Evaluates comparative multinational legal regimes, contrasting Delaware corporate law (anchored to shareholder value) with European civil law structures enforcing stakeholder protections.
- IBM - The Corporate Ecosystem — Translates stakeholder theory into international corporate operations, examining stakeholder salience models, power-interest grids, and cross-border community engagement.
- From Toxic Blitzscaling to Corporate Governance - Investigating Uber's Systemic Reforms — A vital case study detailing the operational and ethical collapse that occurred when blitzscaling prioritized equity valuation over driver welfare, regulatory compliance, and public trust.
🟡 Strategic Management, Stakeholder Models & Institutional Ethics
- Stakeholder Mapping and Analysis — Details practical managerial diagnostic instruments (such as Mitchell-Agle-Wood salience matrices and Mendelow grids) for categorizing, prioritizing, and negotiating stakeholder claims.
- Corporate Social Responsibility (CSR) and Environmental, Social, and Governance (ESG) — Traces how stakeholder theory's normative principles were institutionalized into quantifiable ESG capital allocation metrics and non-financial regulatory reporting.
- The Balanced Scorecard (Kaplan & Norton) — Explores the strategic performance architecture designed to counter short-term financialization by weighting customer, internal process, and organizational learning perspectives alongside equity returns.
- Strategic Alignment — Examines the systemic synchronization of operational capabilities, human capital, and leadership narratives around a unified organizational purpose.
- Lipman-Blumen - The Allure of Toxic Leaders — Diagnoses the psychological and organizational dynamics through which authoritarian executives weaponize internal rivalries and exploit vulnerable stakeholders.
- Innovation Ecosystems — Explores multi-actor co-innovation networks where firms orchestrate collaborative value across complementors, research labs, regulators, and end-users.
🟢 Critical Political Economy, Labor & Societal Impacts
- Welcome to the Family — Deconstructs the paternalistic corporate trope of the "company family," showing how psychological contracts are systematically violated when shareholder primacy reasserts itself during restructuring.
- The Digital Infrastructure of Delusion-A Buddhist Economic and Psychological Analysis of Corporate Culture — Critiques the institutional greed (lobha) and relational alienation of profit-maximizing corporate capitalism, evaluating Benefit Corporations (B Corps) as potential structural antidotes.
- Karl Marx - Economic and Philosophic Manuscripts of 1844 — Foundational political economy critique analyzing the systemic alienation of labor (Entfremdung) that results when workers are reduced to instrumental factors of production.
- Max Weber (1864-1920) — Examines formal legal-rational bureaucracy and the calculative "iron cage" of modern capitalism, providing historical depth to the institutionalization of shareholder financialization.
- William H. Whyte's The Organization Man — Chronicles the post-war corporate conformity and managerial consensus that preceded both the Friedmanite shareholder revolt and Freeman's stakeholder response.
- The Ethics of Taxes — Investigates the moral responsibilities of corporate citizenship, evaluating multinational tax avoidance strategies against the enterprise's reciprocal duties to host societies.
References
- Bebchuk, L. A., & Tallarita, R. (2020). The Illusory Promise of Stakeholder Governance. Cornell Law Review, 106(1), 91–178.
- Berle, A. A., & Means, G. C. (1932). The Modern Corporation and Private Property. Macmillan.
- Business Roundtable. (2019). Statement on the Purpose of a Corporation. Washington, D.C.
- Dodge v. Ford Motor Co., 204 Mich. 459, 170 N.W. 668 (1919).
- Donaldson, T., & Preston, L. E. (1995). The Stakeholder Theory of the Corporation: Concepts, Evidence, and Implications. Academy of Management Review, 20(1), 65–91.
- Freeman, R. E. (1984). Strategic Management: A Stakeholder Approach. Pitman.
- Freeman, R. E., Harrison, J. S., Wicks, A. C., Parmar, B. L., & de Colle, S. (2010). Stakeholder Theory: The State of the Art. Cambridge University Press.
- Friedman, M. (1970, September 13). The Social Responsibility of Business is to Increase its Profits. The New York Times Magazine, 32–33, 122–126.
- Jensen, M. C. (2001). Value Maximization, Stakeholder Theory, and the Corporate Objective Function. Journal of Applied Corporate Finance, 14(3), 8–21.
- Mitchell, R. K., Agle, B. R., & Wood, D. J. (1997). Toward a Theory of Stakeholder Identification and Salience: Defining the Principle of Who and What Really Counts. Academy of Management Review, 22(4), 853–886.
- Revlon, Inc. v. MacAndrews & Forbes Holdings, Inc., 506 A.2d 173 (Del. 1986).
- Schwab, K. (2020). Davos Manifesto 2020: The Universal Purpose of a Company in the Fourth Industrial Revolution. World Economic Forum.
- Stout, L. (2012). The Shareholder Value Myth: How Putting Shareholders First Harms Investors, Corporations, and the Public. Berrett-Koehler Publishers.