Shareholder Primacy (Milton Friedman)
🗂️ Interactive Notebook: Open Study Companion (Video Summary, Flashcards, Mind Map) ↗
Shareholder Primacy (often termed the Friedman Doctrine) is the corporate governance principle asserting that an enterprise's sole social responsibility and fiduciary mandate is to maximize financial profits for its equity owners, operating within legal and ethical rules of open competition. Most famously articulated by Nobel laureate Milton Friedman in 1970, this doctrine transformed modern capital allocation, executive incentives, and Anglo-American corporate law for over four decades.
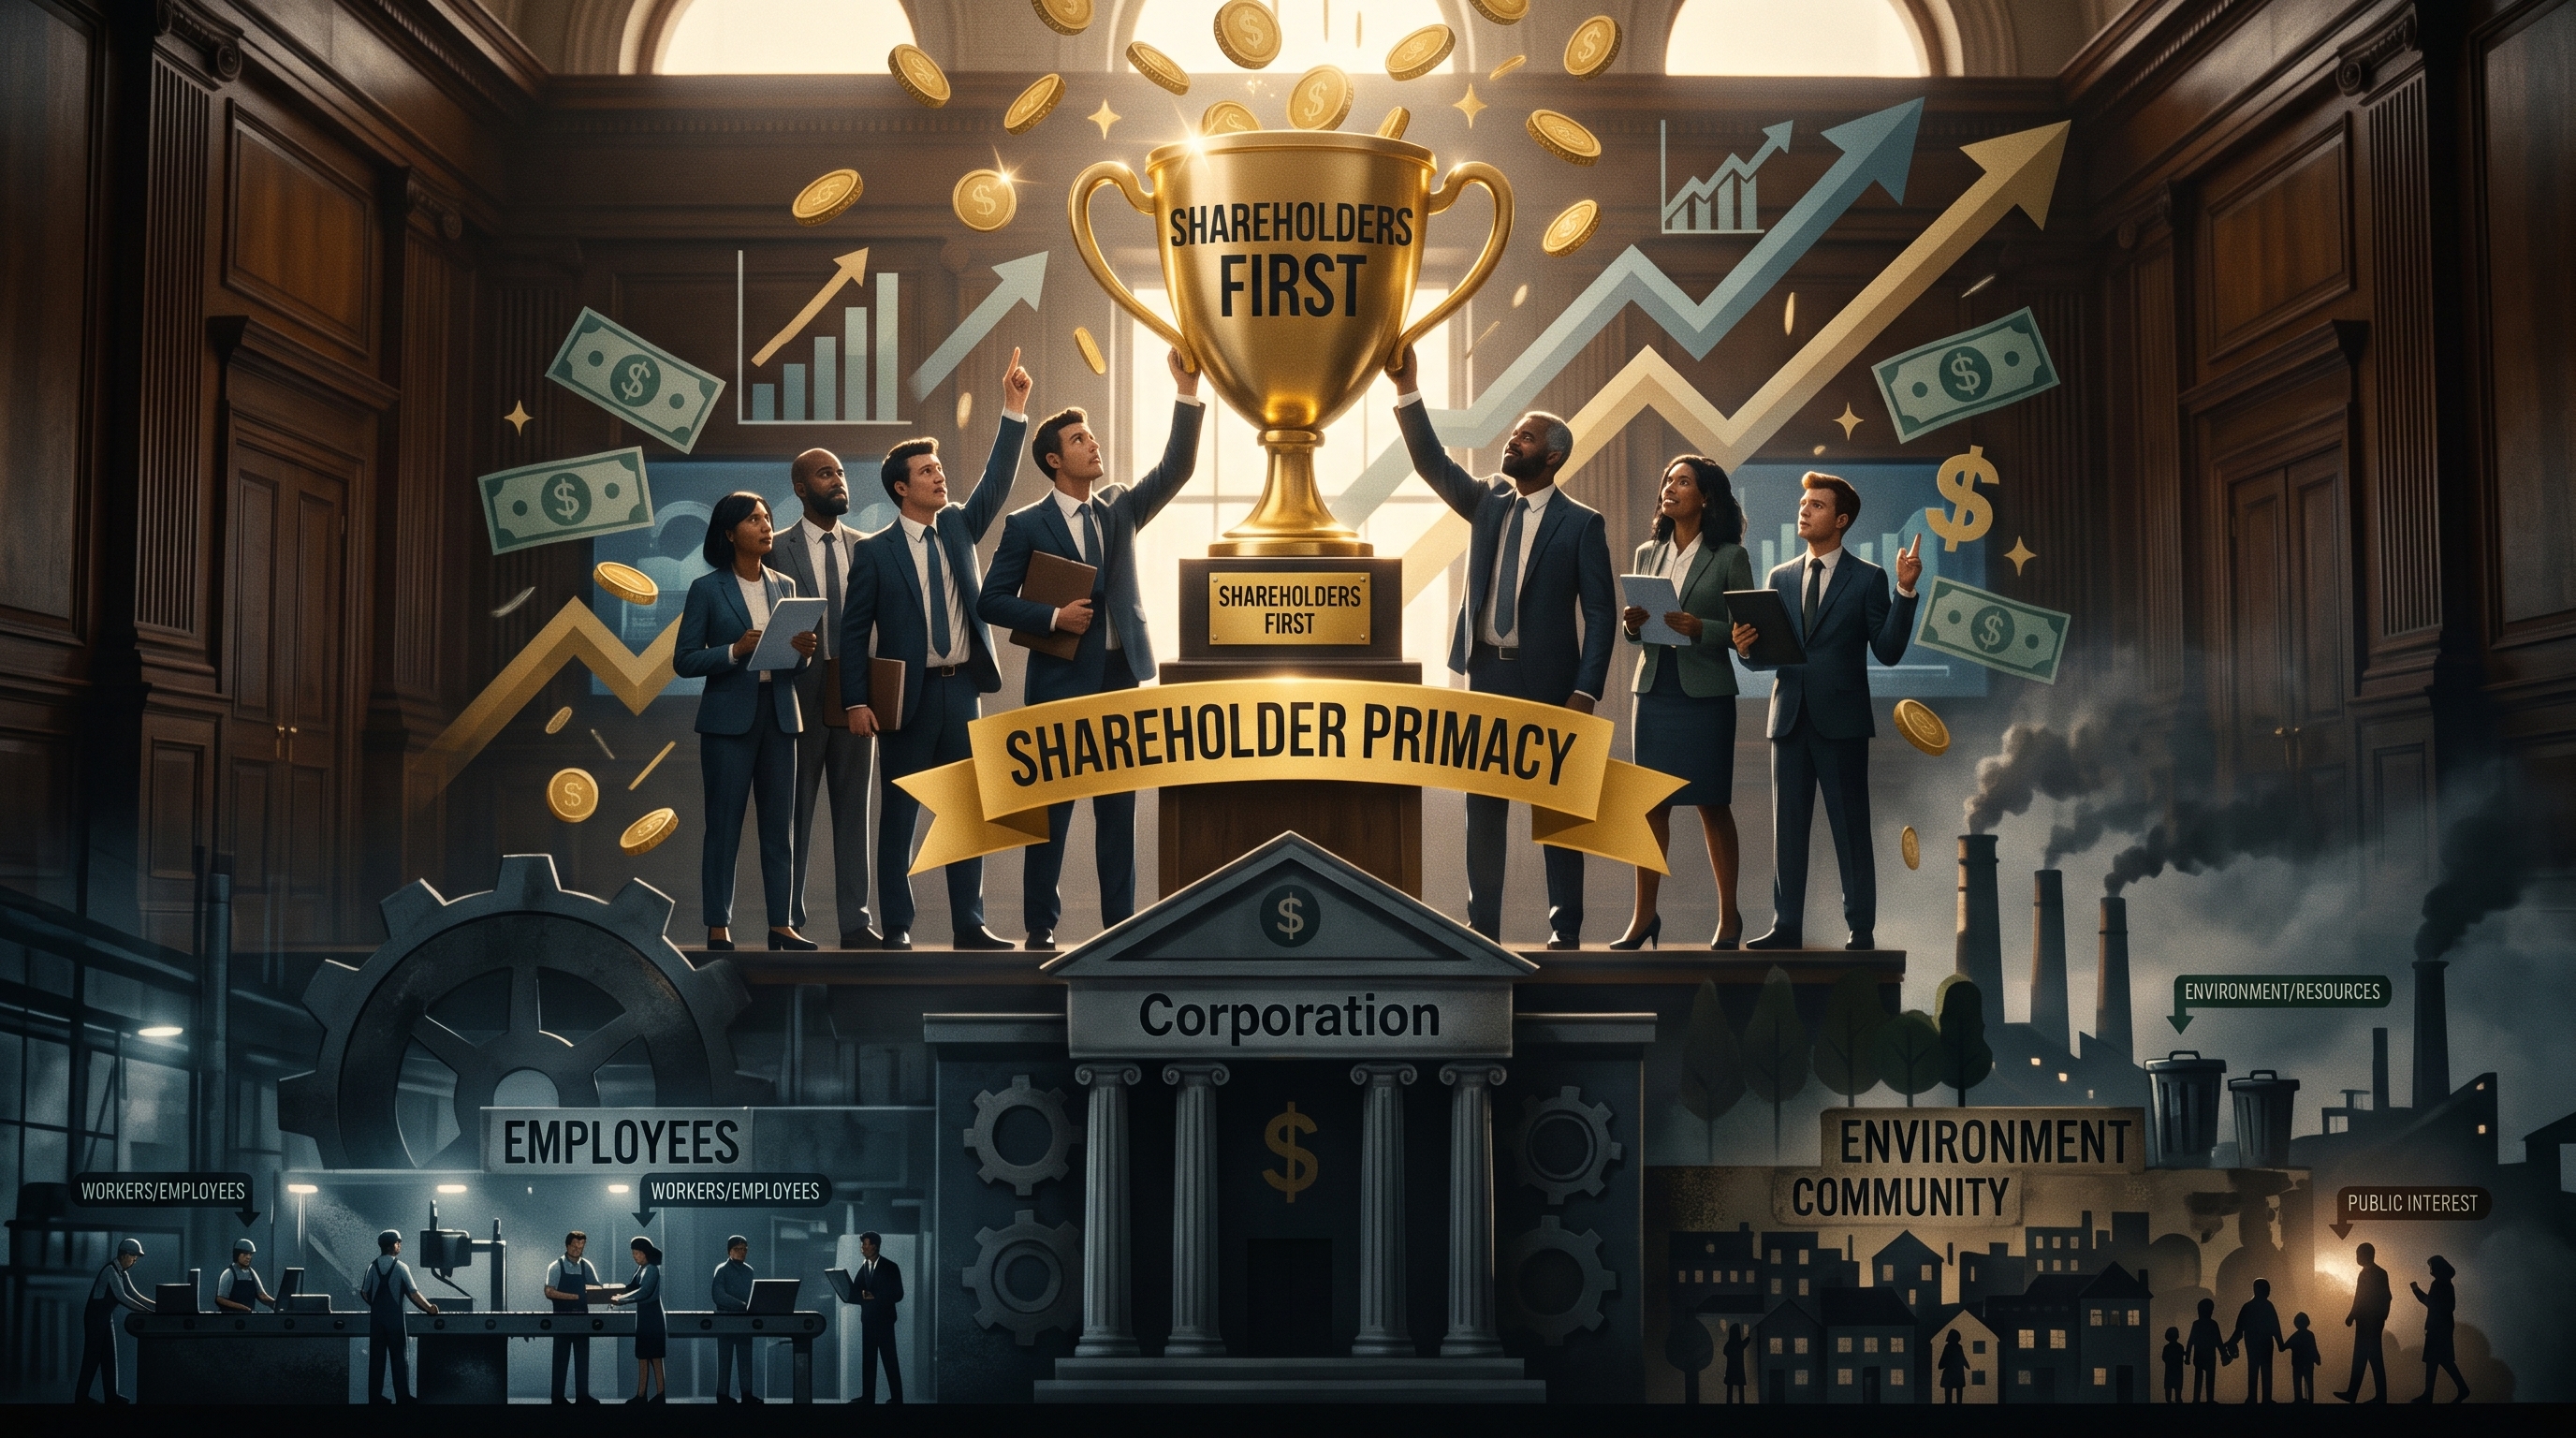
1. The Friedman Doctrine: Core Theses and Foundations
On September 13, 1970, Milton Friedman published a watershed manifesto in The New York Times Magazine titled "The Social Responsibility of Business is to Increase its Profits." Written during an era when American corporate managers viewed themselves as benevolent corporate statesmen balancing labor, community, and capital, Friedman's essay delivered an intellectual offensive against corporate social responsibility (CSR), branding it as economically subversive and fundamentally undemocratic.
"There is one and only one social responsibility of business—to use its resources and engage in activities designed to increase its profits so long as it stays within the rules of the game, which is to say, engages in open and free competition without deception or fraud." — Milton Friedman
Friedman's argument rests upon four foundational logical pillars:
1. Agency Logic and Property Rights
A corporate executive is the employee and legal agent of the owners of the enterprise (the equity shareholders). In that capacity, the manager's primary fiduciary obligation is to run the company in direct accordance with the desires of the principals—which, in commercial firms, is virtually always to generate maximum financial return on invested capital. When executives divert company capital toward unmandated social or philanthropic initiatives, they are unilaterally spending someone else's money for an ambiguous public purpose without authorization.
2. "Taxation Without Representation" and the Political Subversion Argument
Friedman asserted that an executive who allocates corporate revenues toward social goods (such as holding down prices during inflation or eliminating carbon emissions beyond legal thresholds) is effectively imposing a tax on three groups:
- Shareholders, whose residual returns and dividends are curtailed;
- Employees, whose potential wage growth or bonus compensation is depressed;
- Customers, who may pay higher prices to finance non-operational initiatives.
Because the executive is neither an elected public representative nor a civil servant accountable to voters, unilaterally levying and spending what amounts to private tax revenue constitutes undemocratic taxation without representation.
3. The Comparative Advantage Dilemma
Corporate executives possess specialized skills in production, supply chain management, financial arbitrage, and product marketing. They possess no comparative advantage, democratic legitimacy, or specialized expertise in solving complex societal issues such as urban poverty, structural racial inequality, or geopolitical stability. Delegating socio-political decisions to unrepresentative business leaders risks incompetent public policy and distorts market mechanisms.
4. Allocative Efficiency and Market Discipline
In a competitive, free-market economy governed by private property, the price system acts as an indispensable signaling device. Capital naturally flows toward enterprises that generate the highest risk-adjusted returns, signifying that they satisfy consumer desires most efficiently. When firms pursue non-profit social objectives, capital allocation becomes distorted, subsidizing inefficient operations and penalizing disciplined competitors who focus strictly on consumer value creation.
2. Theoretical Lineage: The Chicago School and Agency Theory
While Friedman popularized shareholder primacy in the popular press, the doctrine was codified and institutionalized across academia and financial markets through complementary theoretical breakthroughs:
The Neoliberal Intellectual Foundation
Friedman and his peers in the Chicago School of Economics (including George Stigler and Ronald Coase), influenced by Friedrich Hayek's critique of central planning, posited that competitive markets and decentralized price mechanisms produce superior aggregate welfare than state or corporate paternalism. In this view, individual self-interest disciplined by competition organically generates societal wealth—a direct modern affirmation of Adam Smith's "invisible hand."
Jensen & Meckling's Agency Theory (1976)
In their seminal 1976 paper, Theory of the Firm: Managerial Behavior, Agency Costs and Ownership Structure, Michael Jensen and William Meckling mathematically operationalized the principal-agent relationship first highlighted by Adolf Berle and Gardiner Means in 1932.
Because corporate ownership (diffuse shareholders) is decoupled from operational control (professional managers), self-interested managers face continuous incentives to extract perquisites, build corporate empires, and prioritize managerial safety over risk-taking capital returns. To minimize these agency costs, Jensen and Meckling argued that corporate governance structures must tightly tether managerial incentives to equity valuation.
Eugene Fama and the Efficient Market Hypothesis (EMH)
Eugene Fama's formulation of the Efficient Market Hypothesis posited that public equity prices instantaneously reflect all available market information. Under EMH, a company's share price serves as an objective, unbiased gauge of its true economic viability and capital efficiency. Maximizing share price was therefore celebrated not as reckless speculation, but as the mathematically optimal pursuit of total enterprise value.
3. Legal Foundations, Case Precedent, and Judicial Nuances
Proponents of shareholder primacy frequently cite corporate jurisprudence to claim that corporate directors are legally mandated to maximize short-term share value. However, the legal reality across common-law jurisdictions is considerably more nuanced:
Dodge v. Ford Motor Co. (1919)
The primary judicial precedent cited in favor of shareholder primacy. In 1916, Henry Ford halted special dividend payouts to minority shareholders (including the Dodge brothers), declaring his intention to reinvest surplus capital into lowering vehicle prices and expanding manufacturing employment. The Dodge brothers sued to compel dividend distribution.
The Michigan Supreme Court famously ruled in favor of the Dodge brothers, declaring:
"A business corporation is organized and carried on primarily for the profit of the stockholders. The powers of the directors are to be employed for that end. The discretion of directors is to be exercised in the choice of means to attain that end, and does not extend to a change in the end itself, to the reduction of profits, or to the nondistribution of profits among stockholders in order to devote them to other purposes."
The Business Judgment Rule (BJR)
Despite Dodge v. Ford, Anglo-American corporate law (notably in Delaware, where over half of publicly traded U.S. corporations are incorporated) grants directors immense legal discretion under the Business Judgment Rule. Under Delaware General Corporation Law (DGCL), courts presume that corporate directors act on an informed basis, in good faith, and in the honest belief that their decisions serve the best interests of the company.
Unless self-dealing or outright fraud is proven, courts routinely permit corporate boards to invest in workforce development, charitable initiatives, environmental sustainability, and research with uncertain horizons, accepting the justification that such measures build durable long-term enterprise value.
Revlon, Inc. v. MacAndrews & Forbes Holdings, Inc. (1986)
The singular legal scenario where strict shareholder wealth maximization becomes legally enforceable is known as the Revlon Duty. When a corporate board actively initiates a bidding process to sell the company or break it up, the traditional discretion of the business judgment rule dissolves. At this juncture, the board's fiduciary role narrows exclusively to acting as an auctioneer charged with extracting the highest immediate cash price for shareholders, explicitly barring directors from prioritizing non-shareholder constituencies.
Lynn Stout's Jurisprudential Critique
Legal scholar Lynn Stout (The Shareholder Value Myth, 2012) thoroughly challenged the legal premise of shareholder primacy. Stout established three decisive legal corrections:
- Shareholders do not own the corporation: The corporation is an independent legal person (persona ficta) that owns its own assets. Shareholders own a bundle of contractual securities granting voting rights and residual claims on liquidation or dividend declarations.
- Directors are not literal agents: Legally, corporate directors are independent fiduciaries of the enterprise itself, not at-will agents subject to direct operational commands from individual shareholders.
- The law does not mandate profit maximization: Corporate charters grant boards expansive authority to pursue lawful commercial activities, without dictating any statutory requirement to maximize short-term share price.
4. The Era of Institutionalization: Hostile Takeovers, Equity Compensation, and Financialization
During the 1980s and 1990s, shareholder primacy evolved from an academic theory into the dominant operational ideology of global business, fundamentally reshaping managerial incentives:
| Stage in Financialization | Institutional Mechanism | Operational Outcome |
|---|---|---|
| 1. Ideological Mandate | Friedman Doctrine (1970) & Agency Theory (1976) | Corporate purpose narrowed strictly to maximizing equity returns. |
| 2. Executive Incentive Realignment | Shift from base salary to stock options and restricted shares | Managerial compensation tied directly to quarterly share price spikes. |
| 3. Market Discipline Enforcement | Hostile takeovers, leveraged buyouts (LBOs), corporate raiders | Conglomerates dismantled, non-core units liquidated, headcounts cut. |
| 4. Regulatory Deregulation | SEC Rule 10b-18 (1982 safe harbor for share buybacks) | Trillions shifted from productive capital investment to open-market repurchases. |
| 5. Macroeconomic Realignment | Financial engineering prioritized over operational innovation | Decoupling of wages from productivity, R&D deferred, systemic leverage increased. |
The Hostile Takeover Wave and Corporate Raiders
In the 1980s, corporate raiders (such as Carl Icahn, T. Boone Pickens, and Kohlberg Kravis Roberts) weaponized junk bonds and leveraged buyouts (LBOs) to target diversified corporate conglomerates. They argued that complacent corporate managers were hoarding capital and running firms for personal prestige rather than investor wealth. Conglomerates were broken up, non-core assets liquidated, and workforces slashed to unlock latent shareholder value, cementing market discipline as a ruthless enforcement mechanism.
The Stock Option Revolution
To resolve Jensen and Meckling's agency dilemma, compensation committees pivoted executive pay toward equity-linked instruments, notably stock options and restricted stock units (RSUs). By the late 1990s, executive compensation was overwhelmingly tied to share price appreciation.
While intended to align managers with long-term owners, it inadvertently created perverse incentives: executives became hyper-focused on boosting immediate quarterly earnings per share (EPS) to trigger equity vesting periods before moving on, institutionalizing what critics call "quarterly capitalism."
SEC Rule 10b-18 and Share Buybacks
In 1982, the U.S. Securities and Exchange Commission (SEC) enacted Rule 10b-18, establishing a regulatory safe harbor that protected companies from stock price manipulation charges when repurchasing their own shares. Consequently, corporate capital allocation shifted dramatically: instead of reinvesting earnings into domestic manufacturing plants, workforce wages, or speculative scientific research, Fortune 500 corporations redirected trillions of dollars toward share buybacks to artificially elevate share prices.
5. Comparative Paradigm: Shareholder Primacy vs. Stakeholder Capitalism
The structural contrasts between Milton Friedman's Shareholder Primacy and R. Edward Freeman's Stakeholder Theory (see Stakeholder Theory (R. Edward Freeman) and Difference Between a Shareholder and a Stakeholder) define modern corporate governance:
| Strategic Dimension | Shareholder Primacy Model (Milton Friedman) | Stakeholder Ecosystem Model (R. Edward Freeman) |
|---|---|---|
| Core Purpose of the Firm | Maximizing residual equity profits and share price appreciation. | Creating sustainable, multidimensional value across all constituent networks. |
| Primary Fiduciary Duty | Owed strictly to equity shareholders as capital providers and owners. | Multi-fiduciary duty owed to the ongoing enterprise and all interdependent constituents. |
| Time Horizon | Short-to-medium term; anchored to quarterly earnings and market cycles. | Intergenerational; anchored to operational sustainability and ecosystem viability. |
| Treatment of Non-Investors | Instrumental: employees, suppliers, and communities are means to financial ends. | Inherent: stakeholders possess intrinsic legitimacy and are treated as ends in themselves. |
| View of CSR / Ethics | External distraction or unauthorized "taxation" unless it directly boosts profits. | Indivisible from strategy; rejects the "separation fallacy" between business and morality. |
| Capital Allocation Metric | Return on Equity (ROE), Net Present Value (NPV), and Earnings Per Share (EPS). | Balanced Scorecards, Triple Bottom Line (People, Planet, Profit), and ESG impact. |
| Primary Structural Failure Mode | Short-termism, asset stripping, negative externalities, and systemic fragility. | Diffuse accountability, ambiguous trade-off rules, and managerial paralysis. |
6. Structural Critiques and Negative Externalities
By the early 21st century, the unchecked application of shareholder primacy sparked severe economic, ecological, and societal crises:
1. Chronic Short-Termism ("Quarterly Capitalism")
The relentless pressure to meet quarterly Wall Street consensus estimates incentivized executives to underinvest in long-term research and development, defer preventive infrastructure maintenance, and cut strategic training budgets. As McKinsey research documented, companies managed with long-term orientations consistently outperform short-termist peers in revenue growth, job creation, and market capitalization over ten-year horizons.
2. Externalization of Costs and Environmental Degradation
When corporate success is measured strictly by net income attributable to shareholders, executives face direct incentives to externalize societal and ecological costs. Greenhouse gas emissions, industrial effluent, plastic waste, and localized resource depletion were treated as free disposal mechanisms, creating negative externalities that society and future generations must bear.
3. Decoupling of Worker Productivity from Wage Growth
From 1973 onward—coinciding precisely with the ascendancy of the Chicago School doctrine—the historical correlation between worker productivity and real hourly compensation in the United States decoupled. While productivity increased by more than 60% over subsequent decades, hourly compensation stagnated, with corporate surplus disproportionately captured by executive compensation packages and equity buybacks.
4. Systemic Fragility and The 2008 Financial Crisis
The prioritization of short-term return on equity incentivized excessive leverage and speculative financial engineering across Wall Street investment banks. By designing hyper-leveraged, complex collateralized debt obligations and off-balance-sheet vehicles, financial executives captured massive annual bonuses while accumulating catastrophic systemic risk that ultimately triggered the global financial collapse of 2007–2008.
7. The 21st-Century Shift: Toward Stakeholder Capitalism
In response to persistent systemic crises, the global corporate governance framework is experiencing a profound transition away from rigid shareholder primacy:
The 2019 Business Roundtable Watershed
In August 2019, the Business Roundtable—representing 181 chief executives of America's largest multinational corporations, chaired by JPMorgan Chase CEO Jamie Dimon—formally repudiated its 1997 statement enshrining shareholder primacy. The updated Statement on the Purpose of a Corporation declared that modern enterprises must deliver value to all stakeholders:
- Delivering value to customers;
- Investing in employees through fair compensation, dignity, and training;
- Dealing fairly and ethically with suppliers;
- Supporting local communities and protecting the biosphere;
- Generating long-term value for shareholders who provide capital.
The Rise of ESG Frameworks
Environmental, Social, and Governance (ESG) criteria (see Corporate Social Responsibility (CSR) and Environmental, Social, and Governance (ESG)) transformed from marginal activist initiatives into mainstream capital allocation filters. Institutional asset managers (such as BlackRock, Vanguard, and State Street) recognized that climate change, labor volatility, and lax governance pose material financial risks to long-term enterprise value.
The Benefit Corporation (B Corp) Legal Architecture
To provide directors with ironclad legal protection against shareholder litigation when balancing social objectives, dozens of U.S. states and international jurisdictions established Benefit Corporation statutes. Certified B Corps formally amend their corporate charters, legally obligating leadership to pursue general public benefit alongside financial solvency (see The Digital Infrastructure of Delusion-A Buddhist Economic and Psychological Analysis of Corporate Culture).
European Codetermination Models
International comparative governance highlights viable alternatives to Anglo-American shareholder primacy. In Germany, the system of Mitbestimmung (Codetermination) legally requires large corporations to allocate up to half of supervisory board seats to elected employee representatives, embedding labor directly into long-term strategic decisions and insulating enterprises from reckless short-term financialization.
🎴 Interactive Web Practice (Comprehension Check)
Question 1 (Agency Logic & "Taxation Without Representation"): In Milton Friedman's 1970 essay, why does he characterize an executive spending corporate funds on social causes as committing "taxation without representation"?
Answer: Friedman argues that corporate executives are legally and operationally agents of the shareholders (the residual risk-bearers and owners). In that capacity, the executive's fiduciary duty is to direct enterprise resources toward maximizing profit in accordance with the principals' intent. When an executive redirects corporate capital to non-mandated social objectives—such as restraining product prices or funding public projects—they are effectively spending money that belongs to others. This acts as an undemocratic, unilateral "tax" levied against shareholders (through reduced returns), employees (through curtailed wages), or customers (through higher prices). Because the corporate officer is not an elected public representative operating within constitutional checks, Friedman contends they have usurped a legislative taxing and spending function that belongs exclusively to democratic government.
Question 2 (Jurisprudential Reality & The Business Judgment Rule): How does the Delaware Court of Chancery's application of the Business Judgment Rule complicate the popular belief that corporate boards are legally compelled to maximize immediate share price?
Answer: While popular culture and the 1919 Dodge v. Ford Motor Co. precedent suggest corporate directors have a rigid legal mandate to maximize short-term profits, modern Anglo-American corporate jurisprudence grants boards wide protection under the Business Judgment Rule (BJR). Courts presume that directors act in good faith, on an informed basis, and in the honest belief that their actions advance the best interests of the corporation. As legal scholar Lynn Stout demonstrated, the law recognizes the corporation as an independent legal person, not the property of its shareholders. As long as decisions do not involve self-dealing or fraud, boards are legally permitted to invest in workforce retention, ecological remediation, customer safety, and long-term R&D at the expense of short-term quarterly earnings, provided they can articulate a rational connection to the long-term health of the enterprise. Strict share price maximization is only legally mandated in narrow "Revlon duty" circumstances, where a company is actively undergoing a sale or breakup.
Question 3 (Incentive Structures & The Option Compensation Paradox): How did the 1980s shift toward equity-based executive compensation (designed to solve Jensen & Meckling's agency dilemma) inadvertently generate systemic "quarterly capitalism"?
Answer: Agency theory posited that professional managers, lacking equity stakes, would extract perks and pursue personal security rather than maximizing returns for diffuse owners. To align managerial behavior with shareholder interests, compensation committees shifted executive pay away from fixed salaries toward equity-linked vehicles like stock options and restricted shares. However, this generated perverse secondary effects: because executive stock options vested on short schedules, managers became hyper-incentivized to maximize short-term stock price spikes rather than sustainable, multi-decade enterprise value. To hit quarterly earnings-per-share (EPS) consensus targets, executives frequently engaged in balance sheet financialization—slashing vital R&D budgets, deferring capital expenditures, suppressing workforce wages, and orchestrating massive debt-financed share buybacks (under SEC Rule 10b-18). Thus, the mechanism intended to solve the agency problem amplified managerial short-termism at the expense of systemic organizational resilience.
Resonant Notes
The following notes in the vault share direct thematic, corporate governance, and economic connections with Shareholder Primacy (Milton Friedman):
🔴 Corporate Governance, Agency Theory & Legal Foundations
- Difference Between a Shareholder and a Stakeholder — Establishes the foundational legal, financial, and operational distinctions separating residual equity claimants from broader societal constituents.
- Stakeholder Theory (R. Edward Freeman) — The definitive intellectual counterpoint to Friedman's thesis, articulating multi-fiduciary duty and demonstrating that firm survival relies on balancing interdependent constituent networks.
- IBM - International Business Law — Examines the cross-border legal structures, jurisdictional variance, and fiduciary frameworks governing multinational corporations, contrasting Delaware corporate law with European stakeholder protections.
- IBM - The Corporate Ecosystem — Applies stakeholder salience models (Mendelow, Mitchell-Agle-Wood) to demonstrate how modern enterprises must operate as collaborative networks rather than closed financial extraction vehicles.
- From Toxic Blitzscaling to Corporate Governance - Investigating Uber's Systemic Reforms — A comprehensive case study illustrating the catastrophic governance failure and subsequent board restructuring that occurred when hyper-growth capital allocation operated without fiduciary guardrails.
🟡 Strategic Management, Stakeholder Models & Institutional Ethics
- Stakeholder Mapping and Analysis — Provides practical managerial tools (Power-Interest Grids, Salience Matrices) for identifying, prioritizing, and negotiating with non-investor stakeholders to prevent operational friction.
- Corporate Social Responsibility (CSR) and Environmental, Social, and Governance (ESG) — Traces the operationalization of environmental and societal factors into institutional investment hurdle rates, challenging Friedman's assertion that CSR is illegitimate taxation.
- The Balanced Scorecard (Kaplan & Norton) — Offers a multidimensional strategic performance management framework that directly counteracts short-term financialization by weighting customer, internal process, and learning perspectives alongside financial metrics.
- Strategic Alignment — Analyzes the operational requirement to align enterprise resources, executive KPIs, and organizational structures around coherent, long-term strategic objectives rather than transient quarterly milestones.
- Difference Between Gross Profit and Net Profit & Difference Between Revenue and Profit — Technical financial notes distinguishing between operational gross margins, top-line scale, and bottom-line residual profitability essential for corporate capital allocation analysis.
🟢 Critical Political Economy, Labor & Societal Impacts
- Welcome to the Family — Deconstructs the manipulative corporate rhetoric of the "workplace family," demonstrating how the psychological contract is ruthlessly severed during restructuring cycles when shareholder primacy reasserts itself over employee loyalty.
- The Digital Infrastructure of Delusion-A Buddhist Economic and Psychological Analysis of Corporate Culture — Critiques the institutional greed (lobha) and psychological alienation engendered by shareholder primacy, evaluating Benefit Corporations (B Corps) as structural remedies.
- Karl Marx - Economic and Philosophic Manuscripts of 1844 — Foundational political economy critique analyzing the alienation of labor (Entfremdung) and surplus value extraction inherent in treating human labor strictly as a factor of production for capital accumulation.
- Max Weber (1864-1920) — Analyzes formal rational-legal authority and the "iron cage" of modern bureaucratic capitalism, providing sociological depth to the calculative, metric-driven ethos of Chicago School economics.
- William H. Whyte's The Organization Man — Chronicles the mid-century corporate conformism and bureaucratic collectivism that Milton Friedman sought to overturn with his assertive, free-market individualism.
- The Ethics of Taxes — Engages with the ethical boundaries of tax avoidance and capital distribution, examining Friedman's argument regarding legitimate public taxation versus private corporate allocation.
References
- Berle, A. A., & Means, G. C. (1932). The Modern Corporation and Private Property. Macmillan.
- Business Roundtable. (2019). Statement on the Purpose of a Corporation. Washington, D.C.
- Dodge v. Ford Motor Co., 204 Mich. 459, 170 N.W. 668 (1919).
- Fama, E. F. (1970). Efficient Capital Markets: A Review of Theory and Empirical Work. The Journal of Finance, 25(2), 383–417.
- Freeman, R. E. (1984). Strategic Management: A Stakeholder Approach. Pitman.
- Friedman, M. (1970, September 13). The Social Responsibility of Business is to Increase its Profits. The New York Times Magazine, 32–33, 122–126.
- Jensen, M. C., & Meckling, W. H. (1976). Theory of the Firm: Managerial Behavior, Agency Costs and Ownership Structure. Journal of Financial Economics, 3(4), 305–360.
- Lazonick, W. (2014). Profits Without Prosperity: How Stock Buybacks Manipulate the Market and Leave Most Americans Worse Off. Harvard Business Review, 92(9), 46–55.
- Revlon, Inc. v. MacAndrews & Forbes Holdings, Inc., 506 A.2d 173 (Del. 1986).
- Stout, L. (2012). The Shareholder Value Myth: How Putting Shareholders First Harms Investors, Corporations, and the Public. Berrett-Koehler Publishers.